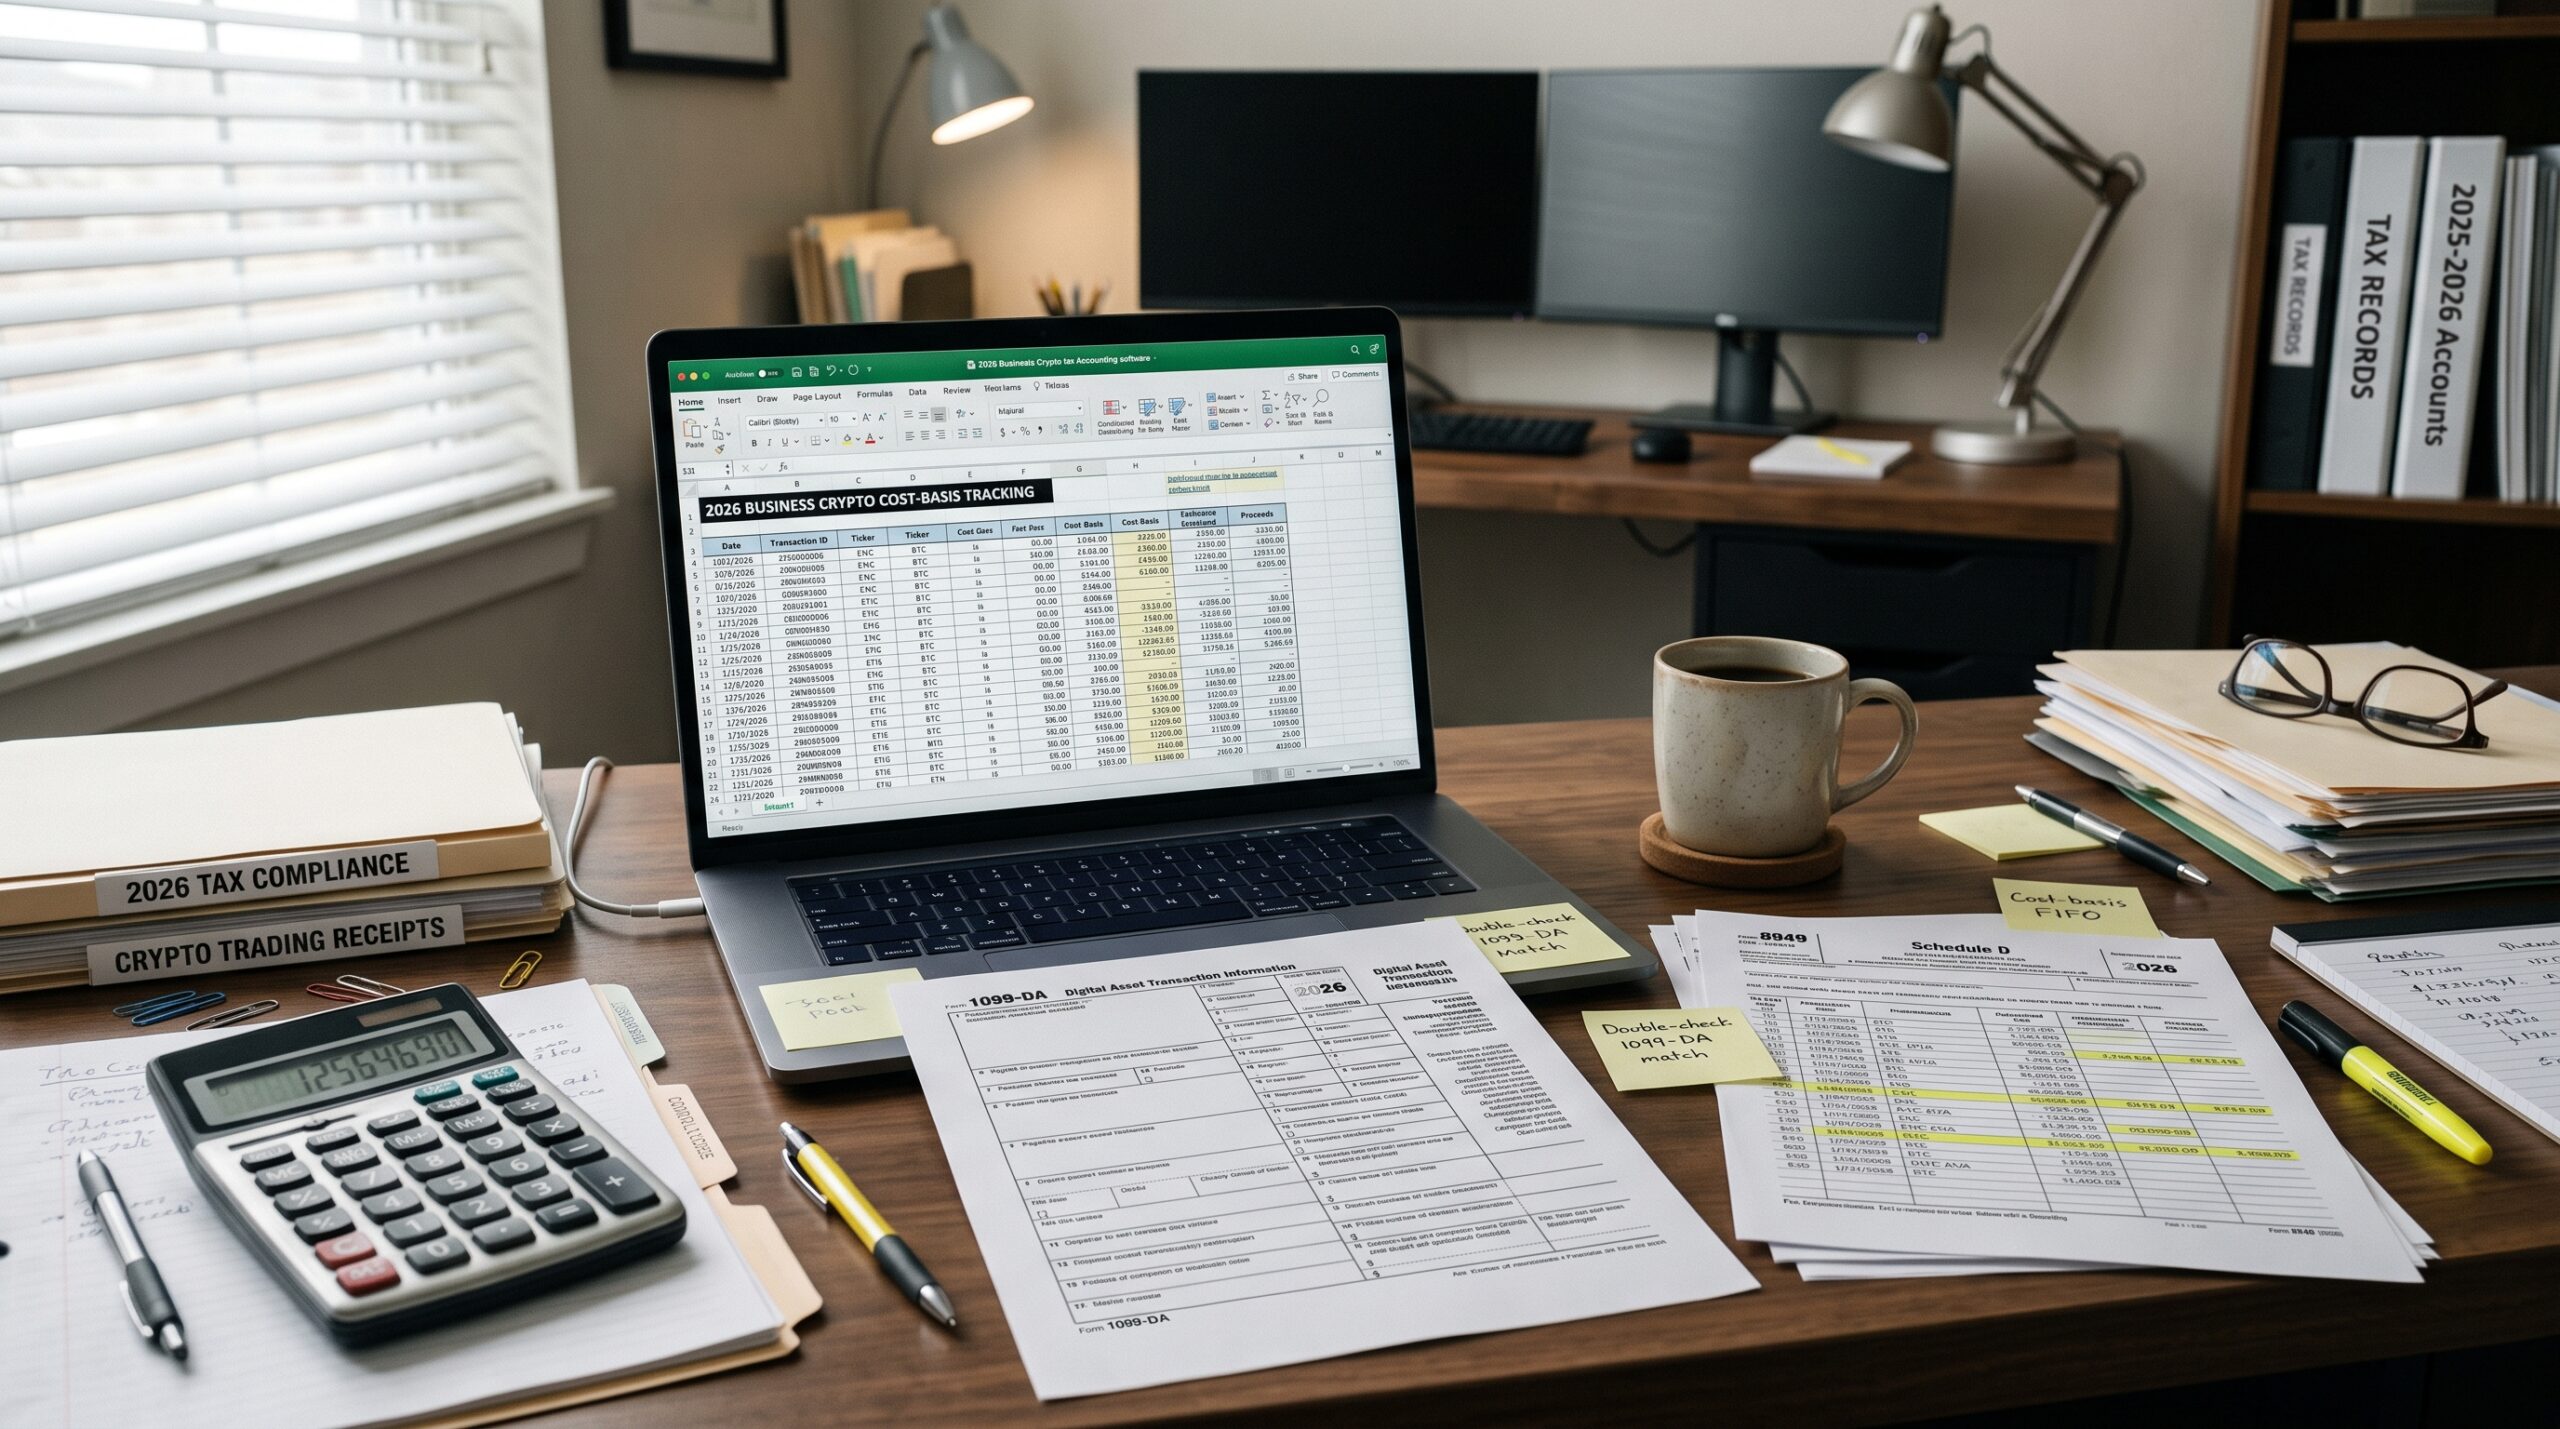
You execute a series of crypto trades for the company and then face the question of how those transactions will appear on the tax return. For businesses the tax treatment of digital assets is more involved than simply tracking gains and losses. Classification as property, ordinary-income events, information reporting, and detailed cost-basis records all come into play. Rules vary by jurisdiction; the discussion below focuses primarily on U.S. federal principles that many companies encounter in 2026, while noting that local and international requirements may differ. This is educational information, not tax advice—consult qualified professionals for your specific situation.
Crypto Treated as Property
Under U.S. federal tax principles, digital assets are generally treated as property rather than as currency. That single classification drives most of the consequences. When a business disposes of crypto—by selling it, exchanging it for another asset, or using it to pay for goods or services—a gain or loss calculation is usually required. The amount of gain or loss equals the difference between the fair market value at disposal and the tax basis (normally the fair market value when the asset was acquired). Holding period determines whether the gain or loss is short-term or long-term.
Ordinary Income Events Common in Business Settings
Not every crypto movement produces capital gain or loss. Accepting crypto as payment for goods or services generates ordinary income equal to the fair market value on the date of receipt. Mining rewards, staking rewards, and many airdrops are also typically treated as ordinary income when the business obtains dominion and control. Paying employees in crypto creates wage income and related employment-tax obligations; paying contractors can trigger Form 1099 reporting. Each of these events requires valuation in fiat currency at the relevant moment and proper characterization on the return.
Cost-Basis Tracking and Record-Keeping
Accurate basis records are essential. For every acquisition the business needs the date, the fair market value in local currency, and the source. When assets move between wallets or platforms, the basis must travel with them. Specific-identification methods, where allowed, can affect the amount of gain or loss realized. Relying solely on exchange reports is risky; businesses should maintain their own transaction logs that can be reconciled to any information returns received.
Information Reporting Developments in 2026
Brokers that take custody of digital assets have expanded reporting obligations. Gross-proceeds reporting on Form 1099-DA applies to transactions effected on or after January 1, 2025. For certain covered assets, basis reporting also begins for transactions effected on or after January 1, 2026. These forms go to both the taxpayer and the tax authority. Importantly, basis is generally not reported for assets acquired before 2026 or transferred into the broker’s account from elsewhere. The appearance of a 1099-DA does not replace the need for internal records; it increases the chance that discrepancies will be noticed.
Business tax returns also contain a digital-asset question that must be answered. Failure to report transactions that should be reported, or material mismatches with broker data, can lead to inquiries.
Practical Compliance Steps for Trading Businesses
Create a consistent valuation policy (for example, using a reputable pricing source at a defined time of day). Record every acquisition and disposition with date, amount, value, and purpose. Separate ordinary-income events from capital transactions in the accounting system. Reconcile internal records to any 1099-DA or similar statements as soon as they arrive. Ensure payroll and contractor-payment processes correctly handle crypto compensation. Hypothetical example: a company receives payment in crypto for services, records ordinary income at the day’s fair market value, later sells a portion of those holdings, and calculates capital gain or loss using the original income-inclusion value as basis. Clean contemporaneous records make the calculations straightforward at year-end.
International and State-Level Considerations
Companies operating across borders face additional complexity. Some jurisdictions treat crypto differently for corporate tax, value-added tax, or withholding purposes. Transfer-pricing questions can arise when related entities move digital assets. State and local rules in the United States may also diverge from federal treatment. Mapping the full set of obligations early prevents surprises.
Governance and Professional Support
Tax treatment should be addressed in the same policy that governs trading and custody. Assign responsibility for record-keeping, valuation, and reconciliation. Engage tax advisors familiar with digital assets before activity scales. Software tools can help, yet they still require correct configuration and oversight. Waiting until year-end to organize records almost always increases cost and error risk.
Tax considerations for business crypto trading in 2026 center on property treatment, the distinction between ordinary income and capital gains, rigorous basis tracking, and expanding information reporting. The introduction of broader 1099-DA basis reporting raises the importance of internal records that can stand on their own. Companies that build clean processes from the first transaction reduce both compliance burden and exposure to later adjustments. Review your current record-keeping, valuation methods, and reporting procedures against the rules that apply to your jurisdictions. Obtain professional advice tailored to your facts, and treat tax compliance as an integral part of the trading operation rather than an afterthought. Accurate books and timely reporting remain the most reliable way to keep the focus on business results instead of tax controversies.
FAQ
Is crypto treated as currency or property for U.S. business tax purposes?
Generally as property. Dispositions usually produce capital gain or loss, while certain receipts (payments for services, mining, staking) produce ordinary income.
Do businesses need to track cost basis even if they receive a 1099-DA?
Yes. Basis reporting on Form 1099-DA is limited, especially for assets acquired before 2026 or transferred between platforms. Internal records remain essential.
What happens when a business accepts crypto as payment?
The fair market value at receipt is generally ordinary income. Later disposal of that crypto produces capital gain or loss measured from that value.
Are there special reporting forms for crypto brokers in 2026?
Yes. Form 1099-DA is used by certain brokers to report gross proceeds (from 2025 onward) and, for some assets, basis (from 2026 onward).
Should a business handle crypto tax issues internally?
Most benefit from advisors experienced in digital-asset taxation, especially once transaction volume or cross-border activity increases. Internal processes should still capture the necessary data from day one.