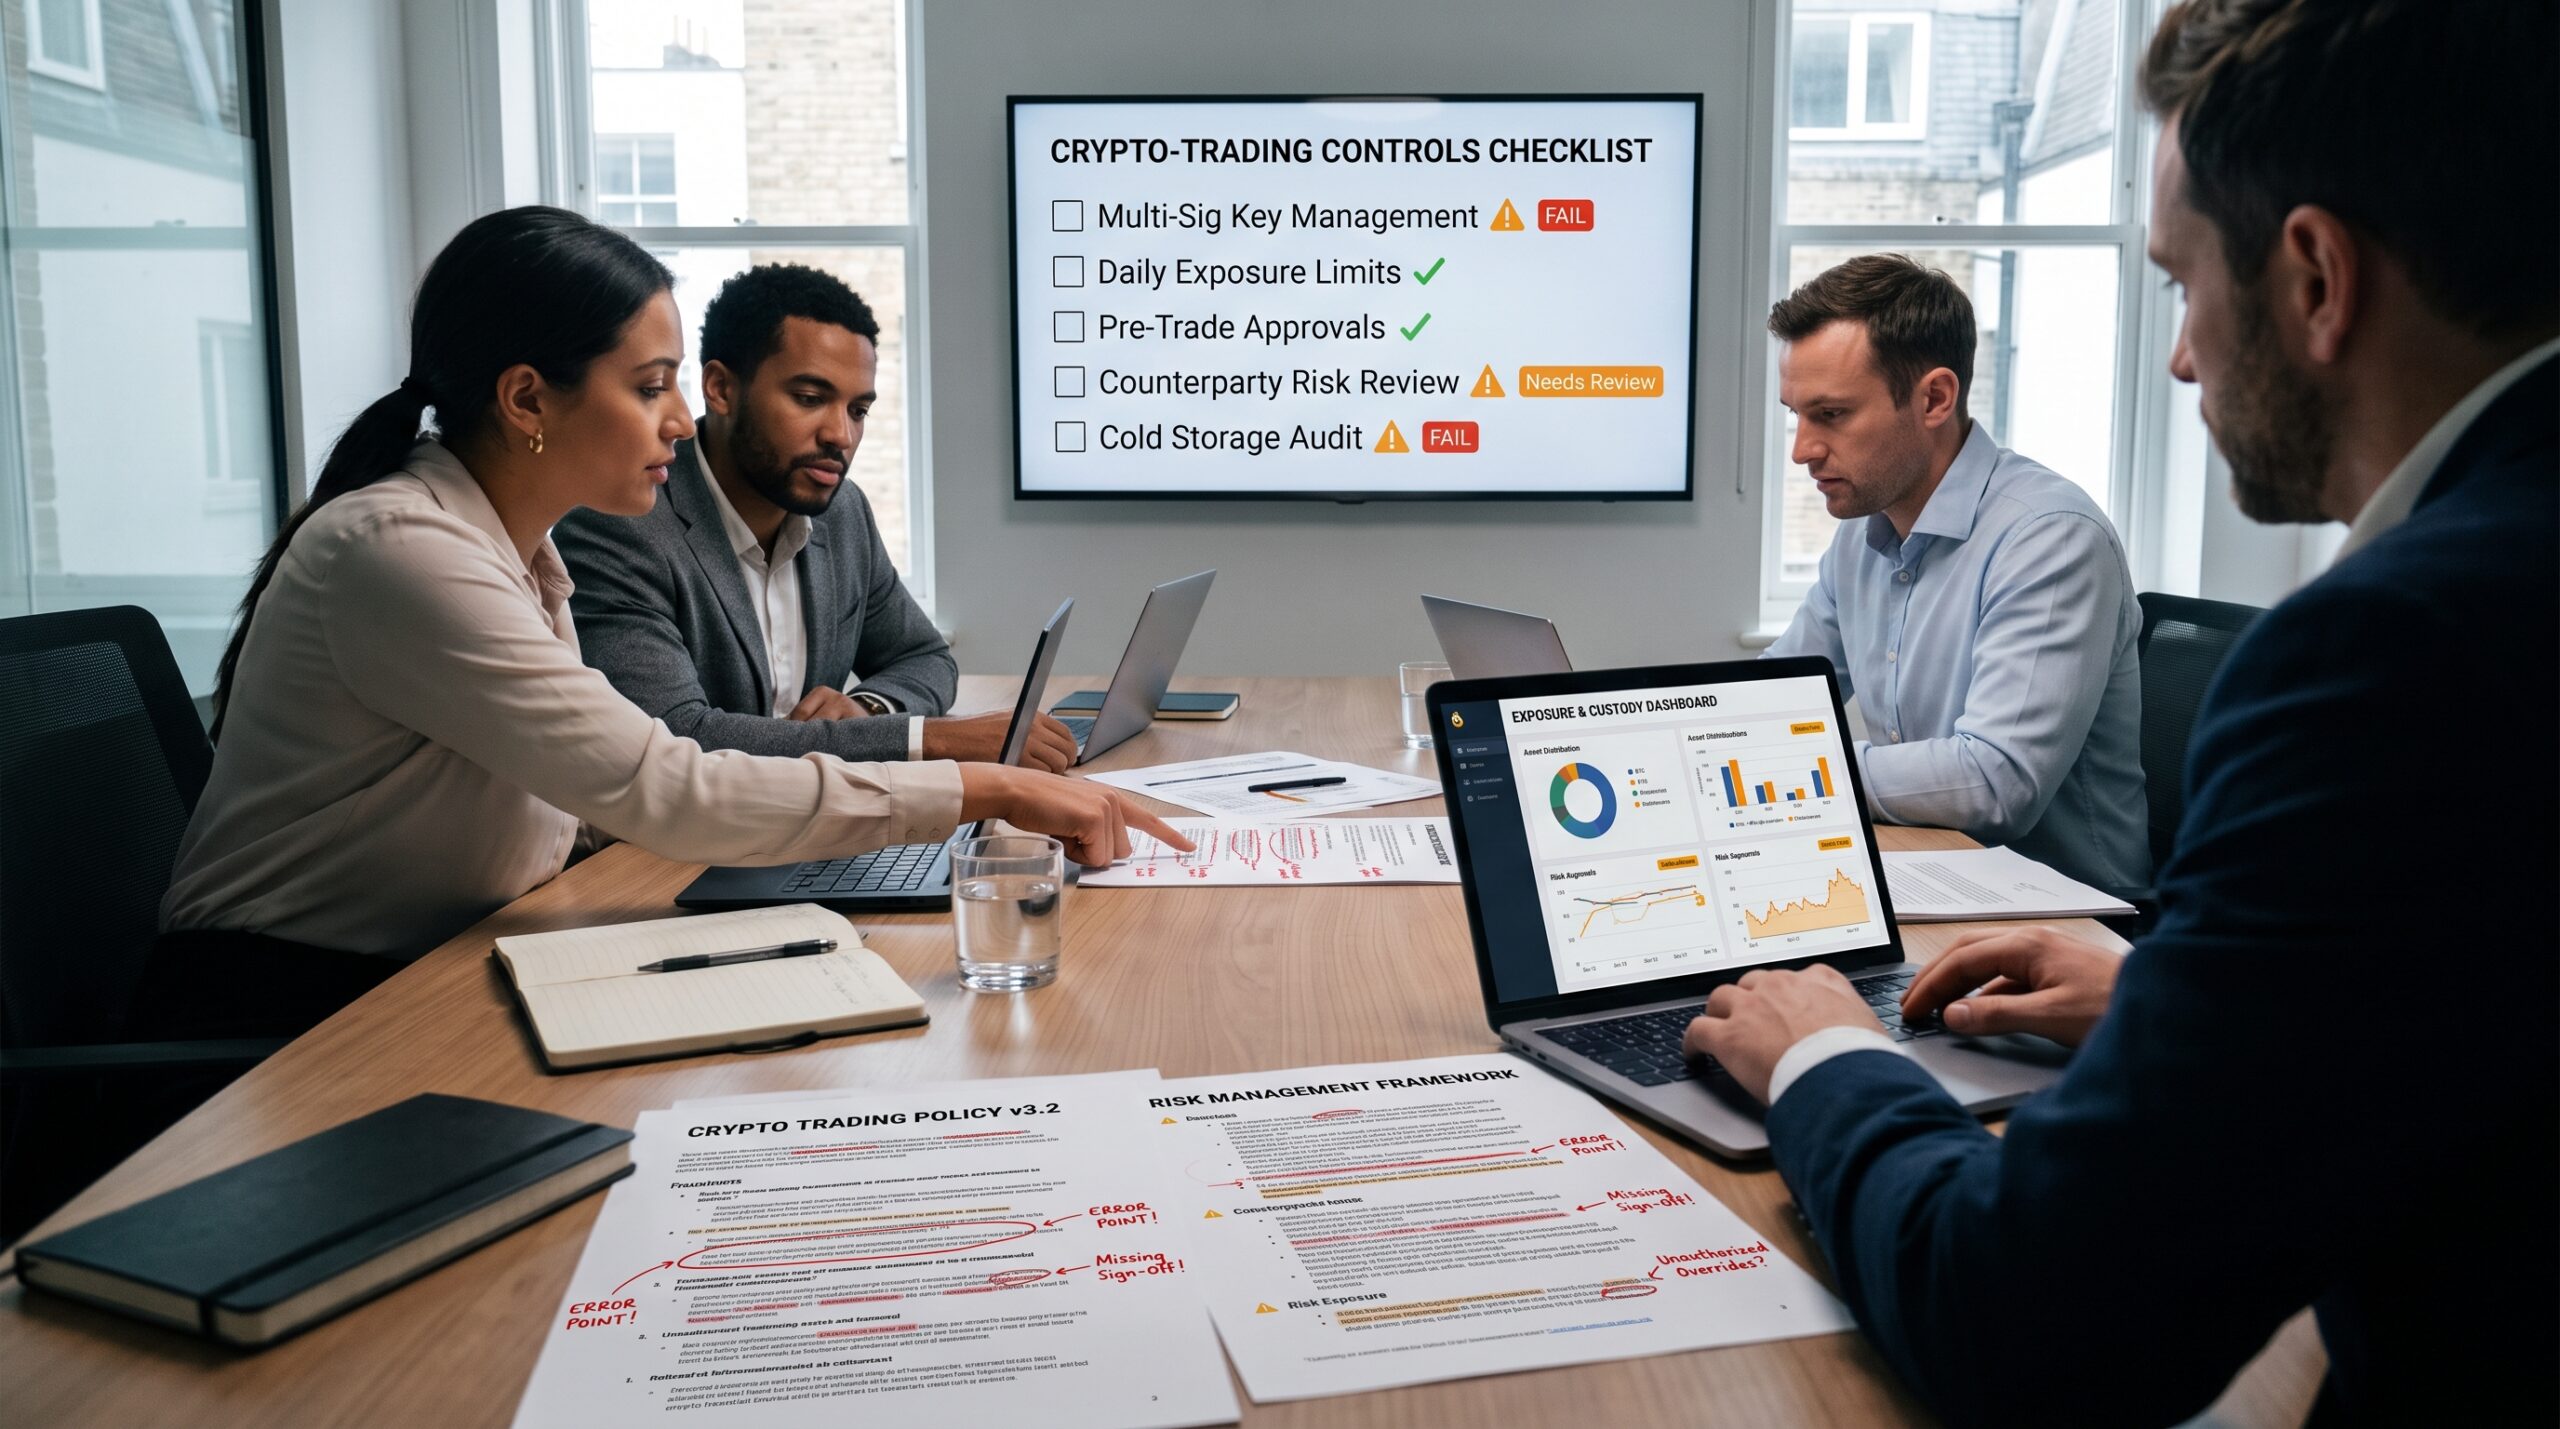
You approve a crypto allocation, the first trades go well, and confidence rises. Then an avoidable error—oversized positions, weak custody, missing records, or ignored limits—turns a controlled experiment into a costly problem. Businesses often stumble not because the market is unpredictable, but because they apply retail habits to an institutional setting. Recognizing the most frequent mistakes helps you build processes that prevent them before capital is at risk.
Starting Without a Written Policy and Hard Limits
Many firms begin trading or holding crypto without a clear objective, maximum allocation, or loss threshold. Activity expands informally during quiet periods and becomes difficult to rein in when volatility arrives. A written policy approved at the proper governance level should define purpose, eligible assets or vehicles, capital limits, and review triggers. Without those boundaries, decisions made under pressure tend to loosen standards exactly when discipline is most needed.
Keeping Large Balances on Exchanges
Leaving substantial company assets on trading platforms exposes the business to exchange failure, hacking, or withdrawal freezes. Institutional practice keeps the majority of holdings with a regulated custodian and moves only operational trading capital to exchanges. Failing to separate custody from execution remains one of the costliest and most common errors. The convenience of instant access rarely justifies the concentration risk.
Oversizing Positions Relative to Volatility and Liquidity
Crypto assets can move far more than traditional treasury instruments. Sizing a position by conviction or by a simple percentage of cash, rather than by its contribution to overall risk and the realistic ability to exit, frequently leads to outsized drawdowns. Effective desks assess how long an exit would take under normal and stressed conditions and set participation limits accordingly. A position that cannot be reduced without major market impact is a structural risk, not an opportunity.
Neglecting Cost-Basis and Transaction Records
Tax and accounting requirements demand detailed records of acquisitions, disposals, valuations, and purposes. Some businesses rely solely on exchange statements or reconstruct history at year-end. Incomplete basis tracking creates reporting errors, potential penalties, and internal control weaknesses. Clean, contemporaneous records—date, value, source, and destination—should be captured from the first transaction and reconciled regularly.
Weak Access Controls and Single Points of Failure
Allowing one person to move funds, approving withdrawals without independent verification, or storing recovery materials insecurely turns operational error or insider risk into permanent loss. Multi-party authorization, dual-control procedures for external transfers, and regular reviews of access rights are standard safeguards. When staff change roles or leave, access must be updated immediately. Security shortcuts taken for speed often become the source of irreversible mistakes.
Ignoring Governance and Independent Oversight
When the same team sets strategy, executes trades, and reports results without independent review, limits erode and problems surface late. Risk, finance, or compliance functions should have visibility into exposures, limit utilization, and exceptions. Regular reporting to a risk committee or equivalent body keeps the activity aligned with the original mandate. Hypothetical example: a company allows an enthusiastic manager to increase crypto exposure after a strong quarter without fresh approval or updated risk assessment. The subsequent decline exceeds what the treasury policy ever intended, and recovery options are limited.
Treating Compliance and Operational Readiness as Afterthoughts
Regulatory classification, reporting obligations, valuation methods, and incident-response plans need attention before activity scales. Businesses that postpone these elements often face rushed fixes under deadline pressure or after an incident. Mapping jurisdictional requirements, testing withdrawal and reconciliation processes, and documenting roles in advance reduce both regulatory and operational surprises.
Crypto trading and treasury activity can serve legitimate business purposes when handled with institutional discipline. The most common mistakes—missing policy limits, exchange concentration, oversized positions, poor records, weak access controls, absent oversight, and delayed compliance—share a common root: treating the asset class as an exception rather than as another managed exposure. Address each of these areas explicitly before increasing capital. Write the rules, enforce dual controls, keep custody institutional, size positions by risk, and review the program on a fixed schedule. The businesses that avoid these errors are usually the ones still operating with confidence after the next period of market stress. Review your current arrangements against this list and close the largest gaps first.
FAQ
What is the single most damaging mistake?
Keeping large balances on exchanges without institutional custody and multi-party controls, exposing the firm to platform and operational failure.
Why do position-sizing errors happen so often?
Teams size by conviction or available cash instead of by volatility, liquidity, and contribution to overall portfolio risk.
How can a business prevent record-keeping failures?
Capture date, value, source, and purpose for every transaction from day one and reconcile internal records to platform statements regularly.
Is a written policy really necessary for small allocations?
Yes. Even modest activity benefits from clear limits, approved vehicles, and review triggers that prevent informal expansion.
When should independent oversight get involved?
From the start. Risk or compliance visibility into limits and exceptions should exist before capital is deployed, not after problems appear.